The Texas Instruments BA II Plus Financial Calculator is my best overall pick for retirement planning calculations, pairing core time-value-of-money functions with a familiar, practical layout. For more advanced financial workflows, the HP 17bII+ offers broader functions, while the online Retirement Calculator is a simpler starting point for estimating a savings target. The main tradeoff is between hands-on control over assumptions and the speed of a guided estimate; a financial calculator can be flexible, but it takes more input and know-how. These tools calculate scenarios, not personalized retirement advice, and results depend on assumptions such as returns, inflation, taxes, and lifespan. Read on for my full comparison and guidance on which style best fits your planning.

Get smart everyday buys delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
Key Takeaways
- The BA II Plus is the strongest all-purpose choice: its time-value-of-money functions suit recurring savings and retirement income calculations without the broader feature set of the HP 17bII+.
- The HP 17bII+ favors breadth over simplicity: its wider financial toolkit can help users with varied calculations, but may be more than a retirement-only planner needs.
- Several listings overlap: the standard BA II Plus and Professional models appear more than once, so buyers should compare the exact model and listing rather than assume each entry represents a distinct tool.
- HP’s 12C models put a different interface first: their calculator style may suit users already comfortable with that approach, while newcomers may prefer a more familiar layout such as the BA II Plus.
- The online retirement calculator answers a different question: it offers a more approachable estimate, while handheld financial calculators give users more direct control over the inputs and calculations.
| Texas Instruments BA II Plus Financial Calculator, Black |  | Best for Straightforward Retirement Scenarios | Brand: Texas Instruments | Model: BA II Plus | Calculator type: Financial | VIEW LATEST PRICE | See Our Full Breakdown |
| Texas Instruments BA II Plus Professional Financial Calculator |  | Best for Advanced Investment Metrics | Brand: Texas Instruments | Calculator type: Financial | Display: 10-digit LCD | VIEW LATEST PRICE | See Our Full Breakdown |
| Texas Instruments BA II Plus Professional Financial Calculator |  | Best for Complex Cash-Flow Modeling | Brand: Texas Instruments | Model: BA II Plus Professional | Display: 10-digit | VIEW LATEST PRICE | See Our Full Breakdown |
| HP 12C Financial Calculator with Case and Cleaning Cloth |  | Best for RPN-Savvy Finance Users | Functions: More than 120 financial and statistical functions | Input method: Reverse Polish Notation (RPN) | Programmable: Stores custom keystroke sequences | VIEW LATEST PRICE | See Our Full Breakdown |
| Texas Instruments BA II Plus Financial Calculator | 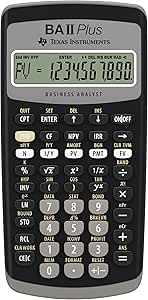 | Best for Worksheet-Based Planning | Brand: Texas Instruments | Model: BA II Plus | Weight: 3.68 ounces | VIEW LATEST PRICE | See Our Full Breakdown |
| HP 10bII+ Financial Calculator with 12-Digit LCD |  | Best for Retirement-Planning Beginners | Brand: HP | Model name: NW239AA | Calculator type: Business, financial | VIEW LATEST PRICE | See Our Full Breakdown |
| CATIGA CF-300 Financial Calculator with 10-Digit LCD |  | Best Value for Core Finance Functions | Brand: CATIGA | Model: CF-300 | Calculator type: Financial | VIEW LATEST PRICE | See Our Full Breakdown |
| HP 17bII+ Financial Calculator with Case and Cleaning Cloth |  | Best for Complex Retirement Scenarios | Brand: HP | Model: 17bII+ | Functions: More than 250 | VIEW LATEST PRICE | See Our Full Breakdown |
| HP 12c Platinum Financial Calculator |  | Best for Advanced Finance Exam Candidates | Functions: More than 130 | Financial calculations: Loan payments, interest rates, amortization, depreciation, IRR, and NPV | Entry modes: RPN and algebraic | VIEW LATEST PRICE | See Our Full Breakdown |
| Retirement Calculator: How Much Money Do I Need to Retire? |  | Best for a Direct Retirement-Savings Question | Product type: Retirement calculator | Stated purpose: Estimate how much money may be needed to retire | Inputs: Not provided | VIEW LATEST PRICE | See Our Full Breakdown |
| investment calculators for retirement planning | Brand | Display | Model | Functions |
|---|---|---|---|---|
| Texas Instruments BA II Plus F | Texas Instruments | LCD; 3.3 cm screen | BA II Plus | Time value of money, NPV, IRR, and bond pricing |
| Texas Instruments BA II Plus P | Texas Instruments | 10-digit LCD | — | — |
| Texas Instruments BA II Plus P | Texas Instruments | 10-digit | BA II Plus Professional | — |
| HP 12C Financial Calculator wi | — | — | — | More than 120 financial and statistical functions |
| Texas Instruments BA II Plus F | Texas Instruments | — | BA II Plus | — |
| HP 10bII+ Financial Calculator | HP | 12-digit LCD with adjustable contrast and on-screen labels | — | Over 100, including probability distributions |
| CATIGA CF-300 Financial Calcul | CATIGA | 10-digit LCD | CF-300 | — |
| HP 17bII+ Financial Calculator | HP | Two-line, 22-character LCD | 17bII+ | More than 250 |
| HP 12c Platinum Financial Calc | — | — | — | More than 130 |
| Retirement Calculator: How Muc | — | — | — | — |
More Details on Our Top Picks
Texas Instruments BA II Plus Financial Calculator, Black
The BA II Plus is a practical pick for retirement savers who want to compare contributions, annuities, loan payments, and investment cash flows without paying for a specialist’s broader toolkit. Its time-value-of-money functions connect savings inputs to future-value estimates, while NPV, IRR, and up to 24 uneven cash-flow streams help compare investments with irregular payouts. Compared with the BA II Plus Professional (B0001EMLZW), it supports fewer cash flows and omits the advanced metrics highlighted for that model, but its simpler feature set may be easier to approach for occasional planning. The tradeoff is a small 3.3 cm LCD, which can make figures harder to read than a larger display. This is a handheld calculation aid, not a guided retirement forecast: users must supply assumptions and interpret the results themselves.
Pros:- Time-value-of-money functions apply to savings, annuities, mortgages, and leases.
- NPV, IRR, and up to 24 uneven cash-flow streams support investment comparisons.
- Bond pricing and four regression options extend it beyond basic savings arithmetic.
- Includes an LR44 battery.
Cons:- The 3.3 cm screen is small for reviewing financial figures.
- It provides no guided retirement-planning workflow, so users must choose and enter assumptions.
- Its cash-flow capacity and feature set are more limited than the BA II Plus Professional models in this lineup.
Best for: Retirement savers who want a familiar financial calculator for checking compound growth, annuity income, and a small set of investment cash flows.
Not ideal for: Users who need guided retirement projections, scenario explanations, or room for more than 24 uneven cash flows; its small screen and manual inputs add friction.
- Brand:Texas Instruments
- Model:BA II Plus
- Calculator type:Financial
- Cash-flow capacity:Up to 24 uneven streams
- Functions:Time value of money, NPV, IRR, and bond pricing
- Display:LCD; 3.3 cm screen
- Power:Battery powered; one included LR44 battery
- Weight:110 g
Our verdict“Choose this BA II Plus for hands-on savings and cash-flow calculations, but pick a Professional model for more advanced analysis or a guided tool for retirement projections.”
Texas Instruments BA II Plus Professional Financial Calculator
For retirement planning that includes investment comparisons beyond ordinary compound-growth estimates, this BA II Plus Professional brings specialized measures such as MIRR, NFV, modified duration, payback, and discounted payback. Those functions can help users examine project returns and bond sensitivity alongside familiar financial calculations. Compared with the standard Texas Instruments BA II Plus (B001JK22YM), this version is the more specialized choice; the standard model covers core time-value-of-money and NPV/IRR tasks without the same advanced metrics. The added capability makes most sense for finance-minded savers who already understand what the measures mean, rather than someone seeking a simple retirement-income estimate. A 10-digit LCD keeps the readout practical, and the included leather-like case offers protection, but the required C battery is a less common power choice than the LR44 specified for the standard BA II Plus.
Pros:- Includes MIRR, NFV, modified duration, payback, and discounted payback.
- 10-digit LCD supports clear entry and review of financial values.
- Leather-like case is included for carrying and protection.
- Adds advanced investment measures beyond the standard BA II Plus feature set.
Cons:- Requires a C battery, a less common format than the LR44 used by the standard BA II Plus.
- Advanced metrics may be unnecessary or difficult to interpret for basic retirement planning.
- Does not provide guided retirement projections or explain which assumptions to use.
Best for: Analytical retirement savers, investment learners, and finance professionals who want MIRR, NFV, duration, and payback calculations alongside core financial functions.
Not ideal for: Beginners seeking a guided retirement calculator or people who only need basic savings projections; the advanced functions add complexity without supplying planning advice.
- Brand:Texas Instruments
- Calculator type:Financial
- Display:10-digit LCD
- Screen size:2.2 inches
- Advanced functions:MIRR, NFV, modified duration, payback, and discounted payback
- Power:Battery powered; requires one C battery
- Enclosure:Leather-like
- Included accessory:Leather-like case
- Weight:4.64 ounces
Our verdict“Pick this Professional model if you can put its advanced investment metrics to work; basic savers are better served by the standard BA II Plus.”
Texas Instruments BA II Plus Professional Financial Calculator
This BA II Plus Professional is the strongest fit here for retirement investors who need to model many uneven cash flows, such as changing contributions, staged withdrawals, or investments with irregular distributions. It supports up to 32 cash flows and includes IRR, MIRR, NPV, and NFV, giving it more room for detailed analysis than the standard BA II Plus, which handles up to 24 uneven streams. Compared with the other Professional listing, B00HX6N2WW, this product data specifically calls out a rugged metal exterior, anti-slip feet, and exam approval; it also describes amortization and depreciation calculations. That physical durability may suit frequent use, but the 10-digit display still limits how much information appears at once. Its finance-focused interface also demands that users know which inputs and assumptions their retirement scenarios require.
Pros:- Handles up to 32 uneven cash flows for more detailed investment scenarios.
- Supports IRR, MIRR, NPV, and NFV analysis.
- Includes time-value-of-money calculations and amortization schedules.
- Rugged metal exterior and anti-slip rubber feet suit frequent handling.
Cons:- The finance-oriented interface may be challenging for users unfamiliar with financial calculator conventions.
- The 10-digit display limits how much information is visible at once.
- Its specialized calculations do not provide guided retirement assumptions or income recommendations.
Best for: Finance students and retirement investors modeling variable contributions or withdrawals across up to 32 uneven cash flows.
Not ideal for: People who want a plain-language retirement forecast or only need simple compound-interest estimates; its specialized functions and compact display can add unnecessary effort.
- Brand:Texas Instruments
- Model:BA II Plus Professional
- Display:10-digit
- Cash-flow capacity:Up to 32 uneven cash flows
- Financial functions:IRR, MIRR, NPV, NFV, amortization, and depreciation
- Power feature:Automatic power down
- Exterior:Rugged metal with anti-slip rubber feet
- Exam approval:CFA and GARP FRM exams
- Warranty:1-year limited warranty
Our verdict“Choose this model over the standard BA II Plus when your retirement scenarios require up to 32 uneven cash flows and you are comfortable supplying the analysis yourself.”
HP 12C Financial Calculator with Case and Cleaning Cloth
The HP 12C suits retirement planners who value a compact, repeatable calculation workflow and are comfortable with Reverse Polish Notation (RPN). Its more than 120 functions cover loan amortization, bonds, depreciation, NPV, and IRR, while programmable keystroke sequences can reduce repeated work when checking similar savings or withdrawal scenarios. Its capacity of up to 20 cash flows is lower than the standard BA II Plus’s 24 and the BA II Plus Professional’s 32, so those Texas Instruments models are better choices for more varied cash-flow modeling. The tradeoff is the RPN learning curve: users accustomed to entering conventional equations may need time to adapt. A carrying case, cleaning cloth, and pre-installed batteries are included, but the calculator does not turn inputs into a guided retirement forecast.
Pros:- More than 120 financial and statistical functions, including NPV and IRR.
- RPN entry can reduce keystrokes for users familiar with that method.
- Programmable keystroke sequences support repeated calculations.
- Includes a carrying case, cleaning cloth, and pre-installed batteries.
Cons:- RPN requires learning a different input method if you are used to conventional entry.
- Its 20-cash-flow capacity is lower than the BA II Plus models listed here.
- Does not offer a guided retirement-planning workflow or interpret results.
Best for: Experienced finance users and retirement savers who know RPN and want programmable keystrokes for repeated financial calculations.
Not ideal for: New calculator users who expect standard equation entry, or investors who need more than 20 cash flows in an analysis.
- Functions:More than 120 financial and statistical functions
- Input method:Reverse Polish Notation (RPN)
- Programmable:Stores custom keystroke sequences
- Cash-flow capacity:Up to 20 cash flows for IRR/NPV analysis
- Financial calculations:Loan amortization, bonds, mortgage payments, NPV, IRR, and depreciation
- Included accessories:Carrying case and cleaning cloth
- Battery:Pre-installed batteries
Our verdict“Pick the HP 12C if you already use RPN and value programmable calculations; choose a BA II Plus model for a larger cash-flow capacity or a more familiar workflow.”
Texas Instruments BA II Plus Financial Calculator
This BA II Plus stands out for retirement savers who prefer dedicated worksheets over entering every calculation from scratch. Its worksheets cover amortization, bonds, depreciation, and compound interest, and memory for previous worksheet values can make it easier to revisit scenarios while adjusting one assumption at a time. It also handles NPV, IRR, and cash-flow analysis, keeping investment comparisons within reach. Compared with the BA II Plus listing B001JK22YM, the product data here emphasizes stored worksheet values, a slide case, and exam approval rather than a stated 24-stream capacity. It is still a financial calculator, not a guided retirement planner: users need to understand the inputs and what the outputs mean. The worksheet approach can also take time to learn, making this less immediate than a basic calculator for casual estimates.
Pros:- Worksheets cover amortization, bonds, depreciation, and compound interest.
- Memory retains previous worksheet values for revisiting calculations.
- Supports cash-flow analysis, NPV, and IRR.
- Slide case helps protect the screen, and a CR123A battery is included.
Cons:- Advanced worksheets can take time to learn.
- The product data does not state a cash-flow capacity, making it harder to judge fit for large scenarios.
- It requires users to select assumptions and interpret results without guided retirement advice.
Best for: Retirement savers who expect to revisit compound-interest, amortization, bond, or depreciation scenarios and want worksheet values retained between calculations.
Not ideal for: People who want a plain-language retirement forecast or prefer a simple interface with no worksheet learning; its specialized worksheets take practice.
- Brand:Texas Instruments
- Model:BA II Plus
- Weight:3.68 ounces
- Dimensions:6.48 x 2.98 x 0.72 inches
- Material:ABS plastic
- Power:One included CR123A battery
- Worksheets:Amortization, bonds, depreciation, and compound interest
- Statistical functions:List-based one- and two-variable statistics with four regression options
- Exam approval:CFA, GARP FRM, and Certified Management Accountants exams
Our verdict“Choose this BA II Plus for reusable worksheet-based calculations; choose the other BA II Plus listing if a stated 24-stream capacity matters more to your analysis.”
HP 10bII+ Financial Calculator with 12-Digit LCD
I’d choose the HP 10bII+ for someone who wants a dedicated financial calculator without taking on the denser feature set of the HP 17bII+. Its over 100 built-in functions give retirement savers tools for finance and probability calculations, while the labeled display and shortcut-focused keyboard can make common calculations easier to enter. The 12-digit LCD also gives more room for numeric results than the CATIGA CF-300’s 10-digit display. The tradeoff is that the product details don’t specify particular retirement-planning functions, so buyers should confirm that its workflow covers their needs rather than assume it offers guided retirement projections. It is a flexible handheld calculator, not a dedicated retirement-planning application; users seeking a tailored estimate of retirement income may prefer a purpose-built tool.
Pros:- Over 100 built-in functions, including probability distributions
- Adjustable display contrast and on-screen labels can make results and functions easier to read
- Keyboard is designed to reduce keystrokes for common functions
- Permitted for SAT, PSAT/NMSQT, and College Board AP tests
Cons:- Product details do not identify specific retirement-planning or cash-flow functions
- Battery-powered operation depends on a battery rather than a stated plug-in option
Best for: Retirement savers who want a general-purpose financial calculator with labeled keys and a readable numeric display for working through their own calculations.
Not ideal for: People who want guided retirement projections or a calculator with specifically documented cash-flow and amortization tools; those features are not listed for this model.
- Brand:HP
- Model name:NW239AA
- Calculator type:Business, financial
- Display:12-digit LCD with adjustable contrast and on-screen labels
- Functions:Over 100, including probability distributions
- Power source:Battery powered
- Compatible tests:SAT, PSAT/NMSQT, College Board AP
- Weight:3.04 ounces
Our verdict“Choose the HP 10bII+ if you want a labeled, general-purpose financial calculator for manually working through retirement questions, not a guided retirement estimator.”
CATIGA CF-300 Financial Calculator with 10-Digit LCD
The CATIGA CF-300 earns its place by naming several functions that matter when modeling retirement savings: TVM, IRR, NPV, cash flow, and amortization. Those tools let a hands-on planner examine growth and payment scenarios, rather than relying only on a broad function count such as the HP 10bII+’s more than 100 functions. Its flip-open hard case is a practical extra for carrying it between home, class, or an office. The compromises are a 10-digit display and a listed 2-inch screen, which may feel less comfortable for users who prefer more visible information. It also requires one nonstandard battery, so battery replacement may be less convenient. I’d favor it for named core finance tools, but not for a large display or a guided retirement forecast.
Pros:- Supports TVM, IRR, NPV, cash flow, and amortization calculations
- Also includes break-even analysis, depreciation, bond pricing, and statistical functions
- Flip-open hard case helps protect it during transport
- Compact 6.46 × 3.15-inch body suits desk, classroom, or on-site use
Cons:- Uses one nonstandard battery, which may be less convenient to replace
- 10-digit LCD and 2-inch screen provide limited display space
- Does not describe a guided retirement-planning or income projection feature
Best for: Budget-conscious retirement savers, finance students, and property owners who want named TVM, cash-flow, IRR, NPV, and amortization functions in a portable calculator.
Not ideal for: People who need a larger display, easy-to-source battery type, or an automated retirement income projection rather than manual scenario calculations.
- Brand:CATIGA
- Model:CF-300
- Calculator type:Financial
- Display:10-digit LCD
- Screen size:2 inches
- Financial functions:TVM, IRR, NPV, cash flow, amortization, break-even analysis, depreciation, and bond pricing
- Power:Battery powered; requires one nonstandard battery
- Dimensions:6.46 × 3.15 inches
- Warranty:1 year
Our verdict“Pick the CATIGA CF-300 if you want a portable calculator with clearly listed cash-flow and time-value functions and can accept its smaller screen and nonstandard battery.”
HP 17bII+ Financial Calculator with Case and Cleaning Cloth
For retirement planning that involves more than a single savings-growth calculation, the HP 17bII+ offers the broadest stated function set in this group: more than 250 functions, plus 28KB of memory for storing lists, variables, and calculations. That capacity could help someone keep working figures together while comparing multiple assumptions. Its support for both RPN and algebraic entry also gives users a choice of input style, unlike a calculator limited to one approach. Compared with the more narrowly described CATIGA CF-300, the 17bII+ emphasizes breadth and stored work; the CATIGA spells out particular functions such as IRR and NPV more explicitly. The HP’s two-line, 22-character display is the main compromise: it can show limited information at once, so reviewing longer calculations may take extra steps.
Pros:- More than 250 functions for finance, accounting, real estate, and statistics
- Supports both RPN and algebraic entry
- 28KB of memory stores lists, variables, and calculations
- Includes a protective case, cleaning cloth, and two pre-installed CR2032 batteries
Cons:- Two-line, 22-character LCD limits how much information is visible at once
- Broad professional feature set may be more involved than needed for a basic retirement estimate
- Product details do not specify a dedicated retirement projection function
Best for: Experienced retirement planners, finance professionals, and detail-oriented savers who want extensive functions, stored calculations, and a choice of entry method.
Not ideal for: Beginners seeking a simple, guided retirement estimate or users who want a large display to view more calculation details at once.
- Brand:HP
- Model:17bII+
- Functions:More than 250
- Entry modes:RPN and algebraic
- Display:Two-line, 22-character LCD
- Memory:28KB
- Power and batteries:Battery powered; two CR2032 batteries included
- Dimensions:6 × 3 inches
- Warranty:2 years
Our verdict“Choose the HP 17bII+ if your retirement work spans many scenarios and stored figures, and you are comfortable working through a compact display.”
HP 12c Platinum Financial Calculator
The HP 12c Platinum suits retirement planning when the questions involve detailed finance work—loan payments, interest rates, amortization, depreciation, IRR, and NPV—rather than a guided estimate of when savings will run out. Its support for RPN and algebraic entry gives experienced users flexibility, while Undo and Backspace keys can help correct input mistakes without restarting a calculation. Compared with the CATIGA CF-300, it includes exam approvals for CFP, CFA, and GARP FRM exams, making it a more targeted fit for finance candidates. The tradeoff is complexity: casual savers may not need its advanced functions. There is also conflicting product information about cash-flow capacity, listing both 30 and 80 cash flows, so I would not rely on that figure without confirmation.
Pros:- More than 130 financial, business, and statistical functions
- Supports both RPN and algebraic entry
- Undo and Backspace keys can make correcting input errors easier
- Includes a protective case, cleaning cloth, and pre-installed batteries
Cons:- Advanced finance focus may be unnecessary for basic retirement estimates
- Product information conflicts on cash-flow capacity, listing both 30 and 80
- No dedicated retirement projection feature is specified
Best for: Finance professionals and CFP, CFA, or GARP FRM candidates who also want a capable handheld calculator for manually modeling retirement-related cash flows.
Not ideal for: Casual retirement savers who want a guided estimate, or buyers who need a confirmed cash-flow storage capacity before choosing.
- Functions:More than 130
- Financial calculations:Loan payments, interest rates, amortization, depreciation, IRR, and NPV
- Entry modes:RPN and algebraic
- Cash-flow storage:Conflicting product details list up to 30 and up to 80 cash flows
- Memory:400 steps
- Exam approval:CFP, CFA, and GARP FRM exams
- Included accessories:Protective case, cleaning cloth, and pre-installed batteries
Our verdict“Choose the HP 12c Platinum if you already use advanced finance calculations or need an exam-approved tool, but verify cash-flow capacity if it matters to your work.”
Retirement Calculator: How Much Money Do I Need to Retire?
Unlike the HP 10bII+ and CATIGA CF-300, which are general financial calculators, Retirement Calculator: How Much Money Do I Need to Retire? is described specifically as a tool for estimating how much money you may need to retire. That makes its stated purpose a closer match for someone starting with a retirement target rather than someone looking for a broad set of finance functions. The limitation is how little product information is available: no calculation inputs, output details, operating format, or supporting features are provided. I can’t compare its calculation depth with the HP 17bII+’s extensive function set or judge whether it handles income, inflation, or investment returns. It may fit a focused first estimate, but buyers who need transparent assumptions or detailed scenario analysis should favor a calculator with specified functions.
Pros:- Purpose is directly focused on estimating a retirement savings target
- May suit users who want a retirement-specific starting point rather than a general finance calculator
- Avoids the need to select among broad financial functions for the stated retirement question
Cons:- No details are provided about inputs, assumptions, or calculation method
- No information identifies output formats or support for multiple retirement scenarios
- No product specifications or additional features are available for comparison
Best for: People beginning retirement planning who want a tool explicitly described as estimating how much money they may need to retire.
Not ideal for: Buyers who need documented assumptions, detailed cash-flow scenarios, or a known set of investment and retirement functions before relying on a calculation.
- Product type:Retirement calculator
- Stated purpose:Estimate how much money may be needed to retire
- Inputs:Not provided
- Calculation method:Not provided
- Output details:Not provided
- Display or operating format:Not provided
Our verdict“Consider this for an initial retirement savings estimate only if its unspecified inputs and calculation method meet your needs.”

How We Picked
I ranked these options by how well they support common retirement-planning tasks: projecting savings growth, converting between periodic contributions and future values, and exploring income or cash-flow scenarios. I also weighed usability, the breadth of financial functions, portability, and how much setup or calculator-specific knowledge each tool asks of the user. Because a handheld calculator does not provide retirement advice or automatically validate assumptions, I favored useful calculation capability over a claim that any device can produce a reliable plan on its own.
The BA II Plus ranks first for its balance of relevant functions and accessible everyday use. The HP 17bII+ ranks higher for buyers who want a broader toolkit, while the online retirement calculator is better for a quick, guided estimate than for flexible financial modeling. Similar BA II Plus entries and the two HP 12C listings are differentiated by their model or interface, not treated as entirely separate categories; repeated listings do not earn an advantage simply for appearing more than once.
| investment calculators for retirement planning | Brand | Functions |
|---|---|---|
| Texas Instruments BA II Plus F | Texas Instruments | Time value of money, NPV, IRR, and bond pricing |
| Texas Instruments BA II Plus P | Texas Instruments | — |
| Texas Instruments BA II Plus P | Texas Instruments | — |
| HP 12C Financial Calculator wi | — | More than 120 financial and statistical functions |
| Texas Instruments BA II Plus F | Texas Instruments | — |
| HP 10bII+ Financial Calculator | HP | Over 100, including probability distributions |
| CATIGA CF-300 Financial Calcul | CATIGA | — |
| HP 17bII+ Financial Calculator | HP | More than 250 |
| HP 12c Platinum Financial Calc | — | More than 130 |
| Retirement Calculator: How Muc | — | — |
Factors to Consider When Choosing Investment Calculators For Retirement Planning
The right calculator depends less on the label “financial” and more on what you want to calculate and how often you will revisit your assumptions. I would choose around the planning task first, then weigh the learning curve and portability.
Match the Tool to the Retirement Question
A savings-growth estimate, a withdrawal plan, and a target retirement balance are related but different calculations. Before buying, write down the question you want answered and the inputs you already know, such as current savings, contribution amount, and time horizon. A handheld financial calculator can give you control over cash flows and timing, but it may not package those inputs into a retirement-specific report. An online retirement calculator may make the first estimate easier, though its available assumptions can be narrower. A common mistake is choosing a device based on its number of functions rather than whether it can handle the calculation you actually need.
Check How Much Control You Need Over Assumptions
Retirement projections change sharply when you adjust the expected return, inflation rate, contribution schedule, or withdrawal period. A calculator is useful only if you can identify which inputs it accepts and understand how they affect the result. Handheld models can support deliberate scenario comparisons, but you must enter and track the assumptions yourself. Guided online tools reduce setup effort, yet may hide or limit some inputs. Avoid treating a single output as a forecast; compare conservative, middle, and higher-return scenarios, and record the assumptions beside each result.
Weigh Learning Curve Against Repeated Use
Financial calculators often require specific key sequences or conventions, so the easiest option is not always the one with the most functions. If you plan to run calculations regularly, a familiar layout and clear instructions can matter more than a long feature list. An advanced model may save effort across varied financial tasks once you learn it, while a simpler tool can get a beginner to a first estimate sooner. Check whether the model’s operating style matches your comfort with calculator inputs. A frequent mistake is buying a sophisticated calculator and then avoiding it because entering a basic scenario feels cumbersome.
Decide Whether Portability Matters
A handheld calculator is useful when you want to work through figures away from a computer or keep a dedicated tool with your planning notes. Cases can help protect a device in a bag, but portability does not make a calculator a complete retirement-planning system. Online tools are easier to access across devices, though they may depend on a website and an internet connection. If you primarily plan at a desk, a portable model may add little value; if you want to recalculate figures during meetings or classes, it can be more practical. Choose around where you will use it, not just its size.
Separate Calculation Power From Planning Advice
A calculator can process inputs, but it cannot decide whether those inputs fit your tax situation, investment mix, health needs, or spending plans. Retirement tools may omit taxes, fees, benefit timing, or irregular expenses, so check what the method leaves out before acting on an output. Handheld financial calculators offer flexibility, but that also puts more responsibility on you to enter the right values and interpret the result. A guided estimate may be easier to read while still relying on simplified assumptions. Use calculator results as scenario comparisons, then seek qualified help for decisions that depend on your full financial picture.
Compare Models and Listings Carefully
This roundup includes repeated BA II Plus Professional entries as well as multiple versions of the BA II Plus and HP 12C. That pattern makes model identification more useful than counting listings: confirm the exact name, included accessories, display details, and operating style before choosing. A professional variant may suit someone seeking a different function set, but a duplicate listing is not a separate planning advantage. If two entries describe the same model, decide based on the exact package and seller information rather than the order in this guide. This check helps prevent buying a second version when the standard model already fits your calculations.
Frequently Asked Questions
Can a handheld financial calculator tell me how much I need to retire?
It can help calculate a target from assumptions you supply, but it does not know your complete retirement needs. You would need to estimate spending, retirement length, income sources, taxes, inflation, and investment returns. Changing those assumptions can produce very different results, so treat the output as a scenario rather than a personal recommendation. A retirement-focused online calculator may offer a simpler starting estimate, while a handheld model gives more direct control over individual calculations. For a decision that affects your long-term plan, verify the assumptions and consider qualified financial advice.
Should I choose the BA II Plus or the BA II Plus Professional?
Start by comparing the specific functions you expect to use rather than assuming the Professional name makes it automatically better for retirement planning. Both are financial calculators in the same family, and either may handle core time-value-of-money work. The Professional model makes more sense if its additional capabilities match calculations you will actually perform. If your needs center on savings growth and basic cash-flow scenarios, the standard BA II Plus may be the more straightforward fit. Since this roundup includes repeated model listings, confirm the exact product name and package before ordering.
Is an online retirement calculator enough, or do I need a financial calculator?
An online tool can be enough for an initial estimate when you want a guided result and do not need to adjust many inputs. A handheld financial calculator is a better fit if you want to work through calculations manually, compare cash-flow scenarios, or use the device for other financial tasks. Neither format guarantees that taxes, fees, inflation, and changing income are fully represented. A practical approach is to use an online estimate to frame the question, then test key assumptions with a calculator or planning professional. Choose based on the depth of analysis you expect to repeat.
Are the HP 12C models a good choice for someone new to retirement calculations?
They may suit a beginner who is willing to learn the HP 12C’s operating style, but familiarity with that style matters. If the input method feels unfamiliar, basic retirement calculations can take longer to set up than on a calculator whose layout you already understand. The BA II Plus is my easier all-purpose recommendation for many buyers, while HP’s 12C options are more compelling when their interface aligns with your existing habits. Check the manual or operating examples before choosing. Comfort with the keystrokes can matter more than having extra functions you rarely use.
What should I do when two listings appear to describe the same calculator?
Compare the full model name and the package details, not just the listing title. Check whether the entry names the Professional version, specifies a display or includes a case or other accessories. Repeated products in a roundup do not represent additional functionality, and a listing difference may reflect packaging rather than a different calculator. If the specifications match, treat the products as the same planning tool and choose the listing whose details are clearest. When specifications are missing or inconsistent, confirm them with the seller before purchasing.
Conclusion
For most buyers, I recommend the Texas Instruments BA II Plus as the best overall balance for retirement-related financial calculations. The standard model is my best value-style choice for users who want core functions without moving to a broader toolkit, while the HP 17bII+ is my best premium pick for people who expect to handle varied financial calculations. Beginners who want a quick starting estimate may prefer the online Retirement Calculator; those set on a handheld device can start with the BA II Plus and learn its core inputs gradually. For specific needs, choose an HP 12C if its operating style suits you, or compare the Professional BA II Plus against the standard model by the functions you will use. No calculator replaces sound assumptions: select the tool that makes it easiest for you to test them.