Personal finance software for beginners should make it easier to see where money goes without burying you in setup or features. I’d put Quicken Classic Deluxe first for a broad starting point, while SayMoney Pro stands out for a more focused money-management approach and Quicken Classic Business & Personal suits people tracking household and business finances together. The main tradeoff is simplicity versus depth: basic tools can be easier to learn, while more involved software may cover more financial tasks but take longer to set up. Older or niche options may fit a particular budgeting style, yet can be less suitable for someone who wants a current, flexible workflow. Read on for the full comparison and help matching each option to your needs.

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
Key Takeaways
- Quicken Classic Deluxe earns the lead for buyers seeking a general-purpose starting point; the business-and-personal edition is more specialized, not a default upgrade for every beginner.
- SayMoney Pro is a focused alternative for people who want to organize personal finances without choosing a business-oriented package.
- Quicken Classic Business & Personal is best matched to users who need household and business money tracked side by side, though that wider scope can add complexity.
- Dave Ramsey’s Personal Finance Software Version 5.3 and Financial Peace are more closely tied to a particular budgeting philosophy, so fit with that method matters more than feature count.
- SavePoint adds another personal-finance option, but beginners should verify platform support, current availability, and their preferred workflow before committing.
| SayMoney Pro Personal Finance Management Software |  | Best for Voice-Assisted Windows Budgeting | Product type: Downloadable software | Supported operating systems: Windows 10, 8, 8.1, 7, Vista, XP, and 2000 | Processor: 1000 MHz | VIEW LATEST PRICE | See Our Full Breakdown |
| Quicken Classic Business & Personal Finance Software (1 Year Subscription, PC/Mac) |  | Best for Beginners with Rental or Business Finances | Platform: PC and Mac | Subscription duration: 1 year | Target audience: New subscribers | VIEW LATEST PRICE | See Our Full Breakdown |
| Quicken Classic Deluxe for New Subscribers (1 Year, PC/Mac Online Code) | 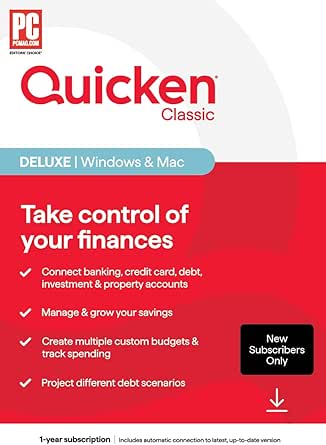 | Best Overall for a Connected Household Money Picture | Platform: PC and Mac | Subscription duration: 1 year | Delivery method: Online code | VIEW LATEST PRICE | See Our Full Breakdown |
| Dave Ramsey’s Personal Finance Software Version 5.3 |  | Best for a Simple, Guided Start | Version: 5.3 | Brand: Dave Ramsey | Product category: Personal finance software | VIEW LATEST PRICE | See Our Full Breakdown |
| SavePoint Personal Finance Software |  | Best for Offline Budgeting and FIRE Planning | Platform: PC and Mac | Connectivity: 100% offline | License type: Lifetime, one-time purchase | VIEW LATEST PRICE | See Our Full Breakdown |
| Financial Peace Personal Finance Software |  | Best for Debt-Focused Beginners | Product name: Financial Peace Personal Finance Software | ASIN: 0963571249 | Type: Software | VIEW LATEST PRICE | See Our Full Breakdown |
| personal finance software for beginner | Platform |
|---|---|
| SayMoney Pro Personal Finance | — |
| Quicken Classic Business & Per | PC and Mac |
| Quicken Classic Deluxe for New | PC and Mac |
| Dave Ramsey’s Personal Finance | — |
| SavePoint Personal Finance Sof | PC and Mac |
| Financial Peace Personal Finan | — |
More Details on Our Top Picks
SayMoney Pro Personal Finance Management Software
Voice input and straightforward budgeting give SayMoney Pro a distinct place in a beginner-focused roundup. It covers everyday tasks such as tracking income, expenses, budgets, and receipts, while CSV import and export can help newcomers move records into or out of the program. PIN protection and encrypted synchronization add privacy options that are useful when financial records are stored digitally. Compared with Quicken Classic Deluxe, SayMoney Pro has a simpler, more focused feature set rather than a broader view of investments and linked accounts. Its main tradeoff is platform age and reach: it is listed for Windows systems, including older versions, and there is no Mac option in the supplied details. Beginners who want modern cross-device syncing or a more expansive financial dashboard may prefer Quicken; Windows users who value voice features and basic expense tracking may find SayMoney easier to approach.
Pros:- Voice input and output offer an alternative to navigating every task with a mouse and keyboard.
- Budget evaluation, expense tracking, and receipt administration cover common beginner money-management needs.
- CSV import and export make it easier to move financial records between tools.
- PIN protection and encryption provide stated safeguards for stored and synchronized data.
Cons:- The listed operating systems are Windows only, limiting access for Mac households.
- Support for older Windows versions and modest system requirements suggest a less modern platform than current subscription software.
- Its supplied feature set is narrower than Quicken Classic Deluxe for users who want connected investment, debt, and property tracking.
Best for: Windows users who are new to budgeting and want voice input, receipt tracking, and basic income and expense tools.
Not ideal for: Mac users or beginners who want a broad connected view of banking, investments, and debt or modern multi-platform support.
- Product type:Downloadable software
- Supported operating systems:Windows 10, 8, 8.1, 7, Vista, XP, and 2000
- Processor:1000 MHz
- RAM:1 GB
- Hard disk space:100 MB
- Key features:Voice input/output, CSV import/export, PIN protection, data encryption, and currency converter
Our verdict“Choose SayMoney Pro if you use Windows and want voice-assisted budgeting and expense tracking without needing a broad, connected financial dashboard.”
Quicken Classic Business & Personal Finance Software (1 Year Subscription, PC/Mac)
Business, rental, and personal finances in one place make this Quicken edition the specialist choice in this group. Its Schedule C and E reports, profit-and-loss statements, and cash-flow analysis speak to owners who need more than a household budget, while rental property tools can keep property activity alongside personal records. Compared with Quicken Classic Deluxe, this edition is better suited to someone with business income or rental reporting needs; Deluxe is the more direct fit for a beginner focused on household spending, savings, debt, and investments. That extra scope can also make the learning curve heavier for a first-time budgeter with no business records to manage. The one-year subscription and new-subscriber restriction are meaningful limits, too. I’d rank it above a simpler tool only when the business and rental features solve a real organizational problem, not just because it offers more functions.
Pros:- Combines personal, business, and rental records in one interface.
- Schedule C and E reports can help organize information relevant to business and rental tax preparation.
- Profit-and-loss statements and cash-flow analysis add useful context beyond a basic household budget.
- Rental property management tools address a need not specified for Quicken Classic Deluxe.
Cons:- Requires a one-year subscription rather than a one-time license.
- Available only to new subscribers, which rules out some returning users.
- Its specialized reports and business functions may add complexity for beginners with personal finances only.
Best for: New subscribers who run a small business or own rental property and want personal finances alongside relevant tax and cash-flow reports.
Not ideal for: Beginners managing only household income and spending, who may find the business-focused tools unnecessary and prefer a non-subscription license.
- Platform:PC and Mac
- Subscription duration:1 year
- Target audience:New subscribers
- Tax reports:Schedule C and Schedule E
- Business reporting:Profit-and-loss statements and cash-flow analysis
- Property tools:Rental property management
Our verdict“Pick this Quicken edition if you are a new subscriber who needs to track business or rental finances alongside household money.”
Quicken Classic Deluxe for New Subscribers (1 Year, PC/Mac Online Code)
Broad household tracking is the reason I rank Quicken Classic Deluxe above the more specialized picks for many beginners. It can bring banking, credit cards, debt, investments, and property into one view, then pair that information with custom budgets and spending tracking. That range gives a newcomer room to start with basic budgeting and add detail as their finances become more involved. Compared with SayMoney Pro, Deluxe is the stronger fit for people who want several financial categories together rather than a focused Windows tool with voice features. It also avoids the business-and-rental emphasis of Quicken Classic Business & Personal, making its scope more relevant to household money. The tradeoffs are the annual subscription and the online-code delivery; this is not a one-time purchase, and it may be more software than someone needs for a simple spending plan.
Pros:- Tracks banking, credit cards, debt, investments, and property in one personal finance tool.
- Custom budgets and spending tracking give beginners a clear starting point for organizing household money.
- PC and Mac support offers broader platform coverage than Windows-only SayMoney Pro.
- A 30-day trial period is included in the supplied product information.
Cons:- Requires an annual subscription rather than a one-time purchase.
- Online-code delivery may not suit buyers who prefer physical media.
- The wider range of tracked financial areas may feel unnecessary to someone who only wants a basic budget.
Best for: New subscribers who want to budget while tracking bank accounts, cards, debt, investments, and property on PC or Mac.
Not ideal for: People who need only a simple offline budget, prefer a one-time license, or want dedicated business and rental reporting.
- Platform:PC and Mac
- Subscription duration:1 year
- Delivery method:Online code
- Target audience:New subscribers
- Financial tracking:Banking, credit cards, debt, investments, and property
- Budgeting tools:Custom budgets and spending tracking
Our verdict“Choose Quicken Classic Deluxe if you want a beginner-friendly starting point that can cover multiple areas of household finances as your needs grow.”
Dave Ramsey’s Personal Finance Software Version 5.3
Ease of use and a take-control focus are the main reasons this software may appeal to a beginner. Its description places it within the Financial Peace University ecosystem and emphasizes getting started with personal money management quickly, rather than presenting a long list of advanced tools. That makes it a more approachable prospect than Quicken Classic Deluxe for someone who wants a guided entry point and does not need to track investments, property, or multiple account types. The gap is that the supplied product information gives little detail about specific budgeting, syncing, or reporting features, so buyers have less to evaluate before choosing it. Version 5.3 may also feel dated beside current PC/Mac subscription offerings. I’d treat it as a focused option for people already drawn to the Financial Peace approach, not as the most flexible choice for a beginner who wants detailed digital tracking.
Pros:- Designed around ease of use, which may help a new user start managing money without a complex feature set.
- The Financial Peace University connection may suit buyers already following that personal-finance framework.
- Focuses on helping users take control of personal finances quickly.
Cons:- The supplied product details do not specify particular budgeting, account-linking, or reporting features.
- Version 5.3 may be dated compared with current digital finance tools.
- Platform compatibility and update support are not specified in the provided product information.
Best for: Beginners who want a simple personal-finance starting point aligned with the Financial Peace University ecosystem.
Not ideal for: Buyers who need clearly documented account connections, advanced reports, current platform details, or the broader tracking offered by Quicken Classic Deluxe.
- Version:5.3
- Brand:Dave Ramsey
- Product category:Personal finance software
- Associated program:Financial Peace University ecosystem
- ASIN:0976963027
- Stated focus:Personal finance management
Our verdict“Consider this software if you want a simple Financial Peace-aligned starting point and do not need the detailed tracking offered by Quicken Classic Deluxe.”
SavePoint Personal Finance Software
Offline privacy and long-range planning set SavePoint apart from the subscription-oriented Quicken choices. Its lifetime license avoids recurring software payments, and its Monte Carlo simulations, balance-sheet tracking, and Sankey diagrams give users tools for exploring financial-independence scenarios beyond day-to-day budgeting. Support for more than 150 currencies and PC/Mac compatibility also make it unusually broad for a locally run option. Compared with Quicken Classic Deluxe, SavePoint places greater emphasis on offline control and FIRE projections, while Quicken is the better fit for beginners who want connected banking and a broader linked-account view. That privacy-first design has a practical cost: users must enter data manually or manage local files, and a two-device limit may not work for a household with several users. Its advanced planning tools could also be more than a new budgeter needs.
Pros:- Runs fully offline, keeping financial tracking local rather than relying on cloud uploads.
- A lifetime license avoids a recurring subscription.
- Monte Carlo simulations, balance-sheet tracking, and Sankey diagrams support deeper planning and FIRE scenarios.
- Supports PC and Mac, more than 150 currencies, and eight listed languages.
Cons:- Lack of cloud synchronization means manual data entry or local file management.
- The license is limited to two devices, which may not suit larger households.
- Advanced FIRE and projection tools may feel excessive for beginners who only want a simple monthly budget.
Best for: Privacy-minded PC or Mac users who want offline budgeting, a one-time license, and tools to model financial-independence plans.
Not ideal for: Beginners who want automatic cloud syncing, connected account tracking, or access across more than two devices.
- Platform:PC and Mac
- Connectivity:100% offline
- License type:Lifetime, one-time purchase
- Included media:8GB USB drive
- Languages:English, Spanish, French, German, Italian, Portuguese, Japanese, and Chinese
- Currencies supported:More than 150
- Device limit:2 devices
Our verdict“Choose SavePoint if offline privacy and long-range FIRE planning matter more to you than automatic syncing and connected accounts.”
Financial Peace Personal Finance Software
Financial Peace Personal Finance Software suits beginners who want a guided approach to budgeting and debt reduction rather than a broad set of money-management tools. Its basis in Financial Peace University principles gives the program a defined framework, which may help new budgeters focus on spending plans and debt goals instead of starting from a blank slate. Compared with Quicken Classic Deluxe, which is positioned as general personal finance software, this pick is more clearly centered on a structured financial approach. The tradeoff is limited product detail: the available information does not specify individual features, supported devices, or how the software handles account connections. I’d choose it only if its method is the main draw; beginners who want clearly documented software capabilities should compare alternatives before committing.
Pros:- Provides a structured approach to personal finance
- Includes a focus on budgeting
- Supports debt-reduction planning
Cons:- Available product information does not describe specific tools or workflows
- Device compatibility and account-connection options are not specified
- The structured method may be less appealing to buyers seeking a general-purpose finance tool
Best for: Beginners who want a structured budgeting and debt-reduction approach based on Financial Peace University principles.
Not ideal for: Buyers who need confirmed details about features, device compatibility, or account connections before choosing finance software.
- Product name:Financial Peace Personal Finance Software
- ASIN:0963571249
- Type:Software
- Category:Personal Finance
- Approach:Based on Financial Peace University principles
- Budgeting:Budgeting tools
- Debt reduction:Debt-reduction support
- Financial planning:Financial planning tools
Our verdict“Choose this if a guided, debt-focused framework matters more to you than having clearly documented software features.”
How We Picked
I ranked these options around the questions a beginner is most likely to face: how much setup is needed, whether the software supports a clear personal budgeting routine, and whether its scope matches a first-time user’s needs. I also weighed the difference between general household finance tools, software that includes business finances, and products associated with a specific budgeting approach. Software that appears more specialized did not automatically rank higher; added scope helps only when a buyer will use it.
Quicken Classic Deluxe leads as the broadest starting point in this lineup, while SayMoney Pro offers a more focused alternative. The business-and-personal Quicken edition ranks lower for general beginners because its extra scope can be unnecessary, and the Ramsey-related options are best for people already drawn to that method. Since product naming and editions do not establish current compatibility or every included feature, I recommend checking supported devices, account connections, and software availability before purchase—especially for older or less familiar offerings such as Version 5.3 and SavePoint.
Factors to Consider When Choosing Personal Finance Software For Beginners
Choosing beginner-friendly software is less about finding the longest feature list and more about picking a tool you will keep using. I’d settle the practical questions below before deciding between a general finance manager, a business-capable package, or a method-driven budgeting program.
Match the software to your first money task
Start by naming the problem you want to solve this month: seeing spending, planning bills, reducing debt, or tracking a small business alongside household finances. A tool aimed at several jobs can be useful later, but extra menus and setup may distract from the task that prompted the purchase. Beginners often choose software based on what it could do rather than what they will actually open each week. If your priority is a simple spending routine, a focused personal-finance tool may be a better fit than a business-capable edition. If you have income and expenses from self-employment, choosing a package that can handle both sides may prevent duplicate tracking. I’d choose for the next year of likely needs, not an imagined future with a much more complicated financial life.
Check how much setup and upkeep you can tolerate
Software only helps when its records stay current, so think about whether you prefer manual entry, connected accounts, or a mix. Automatic connections can reduce repetitive work, but they may require troubleshooting or periodic review; manual entry can feel slower while making each transaction more visible. A common mistake is to assume that connecting accounts means the budget will manage itself. Ask how often you are willing to review categories and correct transactions before choosing a workflow. New users may benefit from starting with a small number of categories and adding detail only when it answers a real question. That habit can matter more than buying the edition with the most tracking options.
Choose a budgeting method you can stick with
Some people want a flexible overview of income and spending, while others prefer a firm plan for assigning money to specific purposes. Products associated with a named budgeting philosophy can make the rules feel clear, but that structure may not suit everyone’s habits. Before committing to a method-driven product, ask whether you want software to guide your decisions or simply record them. A beginner who dislikes strict categories may stop using a tool that feels judgmental or rigid. Someone who wants a defined routine may find that structure easier than designing a budget from scratch. The best fit is the method you can follow consistently, not the one with the strongest claims.
Verify device support and account connections
Do not infer current compatibility from a product name or an older software version. Check whether the edition supports your computer, operating system, and any phone or tablet access you expect to use. If bank connections matter to you, confirm that your institutions are supported and that the connection method fits your comfort level. This check deserves extra attention for older or less familiar offerings, including Dave Ramsey’s Version 5.3 and SavePoint. A beginner can lose momentum quickly if setup depends on an unsupported device or unreliable connection. If the software can work without account syncing, decide whether that fallback suits your routine.
Pay for scope only when it solves a real need
A broader package can make sense when it replaces separate systems or tracks both personal and business finances. It can also add complexity that a household budget does not need. Before choosing a more expansive edition, list the tasks you will use during an ordinary month and see whether its added scope serves any of them. The same principle applies to specialized budgeting software: a structured approach has value when it matches your preferences, not simply because it is distinctive. Avoid treating more tools as a sign of better beginner support. A smaller, clearer workflow can be easier to maintain while you learn your spending patterns.
Plan how you will keep and review your records
Think beyond initial setup: will you want searchable transaction history, recurring budget reviews, or a way to keep records if you stop using the software? Check what export options and data access are available before building a long-term financial record in any one tool. Beginners sometimes focus on importing old transactions and overlook how they will correct mistakes or move their information later. Decide whether you need a detailed history or only a current view of monthly cash flow. A weekly review can keep categories useful without turning money management into a daily chore. Choose a product whose record-keeping routine feels sustainable, rather than one that demands more attention than you can give it.
Frequently Asked Questions
Should I start with Quicken Classic Deluxe or the business-and-personal edition?
I’d start with Quicken Classic Deluxe if you mainly need to manage household finances. The business-and-personal edition is a closer fit when you have business activity to track alongside personal accounts and expect to use both sets of records. Choosing the wider package just in case can add setup and features you may not need. Before deciding, list the financial tasks you need to handle each month and check that the edition supports them on your devices. If business tracking is not part of your routine, the more focused choice is likely easier to learn.
Are Dave Ramsey’s Version 5.3 and Financial Peace suitable for someone new to budgeting?
They may suit a beginner who wants guidance from a particular budgeting philosophy and is comfortable following its structure. A named method can make it easier to decide how to organize money, but it may feel restrictive if you prefer flexible categories or a less prescriptive tool. Check the current software availability, device compatibility, and account connection options before buying, especially for Version 5.3. Also decide whether you want software to teach a process or simply help record transactions. A good match depends on your willingness to follow that approach, not on how new you are to budgeting.
Do I need bank syncing to manage my money as a beginner?
No. Account syncing can save data-entry time, but it is not required to start making a budget or understanding spending. Manual entry may help you notice purchases and learn your patterns, though it asks for regular effort. If you want syncing, confirm that your bank is supported and understand how you will review imported transactions for errors or missing items. You can also begin with a small number of accounts rather than connecting everything at once. The right choice is the one you can keep accurate without making money management feel like another full-time task.
How can I tell whether SavePoint or another less familiar product is a safe fit?
Before relying on a less familiar product, confirm that it is currently available and runs on your computer or mobile devices. Look for clear information about data export, account connections, and what happens to your records if you stop using the software. Avoid importing every account before you know how the tool handles categories and corrections; try a limited set of records first if possible. Check whether the product supports the specific tasks you need instead of assuming its name guarantees broad functionality. If current support or compatibility is unclear, a more established, broadly scoped option may be the lower-friction starting point.
When is a more feature-rich finance program worth the extra complexity?
It is worth considering when the additional capabilities solve a recurring problem, such as tracking business and household finances in one place. It is less compelling when the extra scope is only a possibility you may never use. Write down the reports, records, or workflows you expect to use in a typical month, then compare those needs with the setup required. Beginners can often learn more from a simple routine they maintain than from a large feature set they rarely open. If your needs grow, you can reassess after you have a clearer picture of your finances.
Conclusion
For a general-purpose starting point, I recommend Quicken Classic Deluxe as the best overall pick in this lineup. SayMoney Pro is the best value-style choice for someone seeking a more focused personal-finance option, while the business-and-personal Quicken edition is the best premium-style fit for buyers who genuinely need both kinds of tracking. For beginners who want a defined budgeting philosophy, Dave Ramsey’s Personal Finance Software Version 5.3 or Financial Peace may suit their preferences, provided current availability and compatibility check out. SavePoint is a specific alternative for readers willing to verify its support and workflow before committing. If you are undecided, choose the least complicated option that covers the money tasks you need to manage now.
Halloween Picks
halloween
As an affiliate, we earn on qualifying purchases.