Retirement calculators come in two flavors: quick answers and deep planning. If you just want a reality check on whether your savings are on track, a free online calculator will do the job in five minutes. If you want to model tax brackets, Social Security claiming ages, sequence-of-returns risk, and withdrawal order, you need something heavier — and that’s where the books and paid tools on this list earn their keep.

Get smart everyday buys delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
My top pick for most people is The Retirement Dilemma, which pairs fifteen proprietary calculators with the context you need to actually interpret their outputs. For readers who want a single, focused answer to the question “how much do I need to retire?”, the aptly named Retirement Calculator: How much money do I need to retire? is the better starting point. The main tradeoff throughout this roundup is depth versus speed: the more assumptions a tool lets you control, the more ways you can get it wrong.
Key Takeaways
- The Retirement Dilemma is the strongest all-around pick because it bundles 15 proprietary calculators with explanations of the dilemmas each one addresses — outputs come with context, not just numbers.
- Retirement Calculator: How much money do I need to retire? is the best single-question tool: fast, focused, and ideal for a first savings target.
- Free tools from Fidelity, Vanguard, and Schwab are excellent for tracking against accounts you already hold there, but they underperform for multi-account or self-employed situations.
- Monte Carlo engines like FIRECalc and NewRetirement answer a different question than deterministic calculators: not ‘will I hit my number’ but ‘will my money survive bad decades’.
- The biggest differentiator isn’t math quality — nearly all of these use sound models — it’s whether the tool explains its assumptions or hides them.
| The Retirement Dilemma: The 8 Retirement Planning Dilemmas You Need to Understand and Overcome, 15 Proprietary Calculators Included |  | Best Overall | Format: Print / digital book | Calculators included: 15 proprietary | Core framework: 8 retirement planning dilemmas | VIEW ON AMAZON | See Our Full Breakdown |
| Retirement Calculator: How much money do I need to retire? | 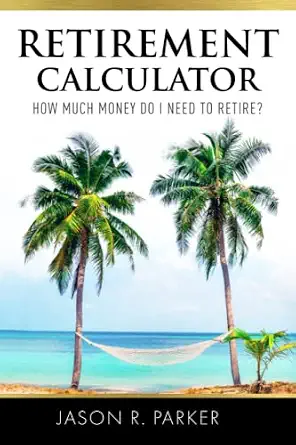 | Best for a Quick Baseline Number | Format: Print / digital book | Core output: Single retirement savings target | Inputs required: Spending, income sources, time horizon | VIEW ON AMAZON | See Our Full Breakdown |
| retirement planning calculator | Format | Best use stage | Data entry | Account syncing |
|---|---|---|---|---|
| The Retirement Dilemma: The 8 | Print / digital book | 10-15 years before retirement | Manual | No |
| Retirement Calculator: How muc | Print / digital book | Early to mid-career | Manual, minimal | No |
More Details on Our Top Picks
The Retirement Dilemma: The 8 Retirement Planning Dilemmas You Need to Understand and Overcome, 15 Proprietary Calculators Included
This book earns the top spot because it does something no free calculator manages: it frames retirement planning as a set of eight recognizable dilemmas — claiming Social Security too early versus late, spending more now versus later, safety versus growth — and then hands you a purpose-built calculator for each one. Instead of one intimidating spreadsheet with forty inputs, you get fifteen focused tools, each answering one question well.
Compared with the Retirement Calculator book below, which chases a single number, this one acknowledges that retirement planning is a chain of tradeoffs, not a single target. The calculators are genuinely proprietary rather than repackaged 4% rule worksheets, and the text explains why each dilemma exists before showing you the math. That framing matters: it teaches you to spot flawed advice elsewhere.
The tradeoff is commitment. This is a book first and a calculator second, so if you want a number in five minutes, it will frustrate you. And because it’s print, the calculators can’t pull live market data the way Fidelity’s or Empower’s tools can — you supply every input yourself. For readers willing to spend a weekend instead of five minutes, it’s the most complete package here.
Pros:- Fifteen calculators each address one specific dilemma, so inputs stay manageable
- Teaches interpretation, which prevents overconfidence in a single magic number
- Covers decisions most free calculators ignore, like claiming strategy and withdrawal order
- Structured around real decisions rather than abstract projections
Cons:- Requires reading and manual data entry — not a five-minute tool
- Print format means no live account syncing or automatic market updates
Best for: Pre-retirees within 10-15 years of retirement who want to understand the tradeoffs behind their numbers, not just the numbers themselves
Not ideal for: Anyone wanting an instant, no-reading-required answer from a web form
- Format:Print / digital book
- Calculators included:15 proprietary
- Core framework:8 retirement planning dilemmas
- Best use stage:10-15 years before retirement
- Data entry:Manual
- Account syncing:No
- Depth:Advanced
- Time investment:Several hours
Our verdict“The most educational and complete retirement planning package on this list — if you’ll invest the time to use it properly.”
Retirement Calculator: How much money do I need to retire?
Sometimes you don’t need a planning system — you need a number to aim at. This book delivers exactly that: a straightforward method for calculating your retirement number based on your spending, expected income sources, and time horizon. Where The Retirement Dilemma asks you to work through eight tradeoffs, this one answers the single question most savers actually start with.
Its strength is speed and clarity. The method is easy to follow without a finance background, and it produces a concrete savings target you can act on this week. Compared with the free Fidelity or T. Rowe Price calculators, it asks for fewer inputs, which makes it less precise but far less intimidating — a reasonable exchange when you’re decades from retirement and precision is illusory anyway.
The limitation is the flip side of that simplicity. It won’t help you decide when to claim Social Security, how to sequence withdrawals, or whether a bad market decade could sink an otherwise sound plan. Think of it as chapter one of your retirement plan, not the whole book — and if you’re within five years of retiring, you’ll outgrow it quickly.
Pros:- Produces an actionable savings number fast
- Minimal jargon — accessible without any finance background
- Focused scope keeps you from getting lost in unnecessary inputs
- Cheaper and faster than full planning software or advisory sessions
Cons:- Too simple for multi-account or near-retirement situations
- Doesn’t address market volatility, taxes, or withdrawal sequencing
Best for: Younger savers and mid-career workers who want a clear savings target without wading through planning theory
Not ideal for: Near-retirees with pensions, taxable accounts, or claiming-age decisions to make
- Format:Print / digital book
- Core output:Single retirement savings target
- Inputs required:Spending, income sources, time horizon
- Best use stage:Early to mid-career
- Data entry:Manual, minimal
- Account syncing:No
- Depth:Beginner
- Time investment:Under an hour
Our verdict“The best fast answer to the most common retirement question — just don’t mistake it for a complete plan.”

How We Picked
I evaluated each calculator against three criteria. First, model quality: does the tool account for inflation, taxes, Social Security timing, and market volatility, or does it assume a flat return forever? Second, usability: a calculator that takes an hour to configure is worthless to a beginner, while a three-input tool frustrates a near-retiree with a complicated portfolio. Third, transparency: I favored tools and books that show their assumptions and let you change them, because a confident answer built on hidden inputs is worse than an honest range.
For the books, I looked at whether the included calculators were genuinely proprietary methods or repackaged rules of thumb, and whether the surrounding text teaches you to interpret results. No tool was ranked on brand familiarity alone — several big-name calculators landed mid-pack because they lock you into their own account ecosystem.
| retirement planning calculator | Data entry | Depth | Time investment |
|---|---|---|---|
| The Retirement Dilemma: The 8 | Manual | Advanced | Several hours |
| Retirement Calculator: How muc | Manual, minimal | Beginner | Under an hour |
Factors to Consider When Choosing 11 Best Retirement Planning Calculators
Choosing among these calculators comes down to three questions: how complex your situation is, how much time you’ll invest, and which decision you’re actually trying to make. A tool that’s excellent for one buyer is wrong for another — that’s why this list spans books, free web tools, and premium software.Deterministic vs. Monte Carlo — and Why It Matters
Deterministic calculators (the Retirement Calculator book, Flexible Retirement Planner) apply a fixed return and inflation rate and give one answer. They’re easy to audit but can mislead if the assumed return is generous. Monte Carlo tools (Vanguard, Empower, T. Rowe Price) run thousands of scenarios and report a success probability, which is more honest about uncertainty but tempts people to chase an arbitrary 90% figure. The best approach is often both: a deterministic plan you understand, stress-tested by FIRECalc or a Monte Carlo engine.
Match the Tool to Your Decision
If your question is how much to save, start with the Retirement Calculator book or Vanguard’s tool. If it’s when to claim Social Security, use the Open Social Security calculator. If it’s can I afford to retire this year, you need NewRetirement, The Retirement Dilemma, or T. Rowe Price’s income model. Picking the tool that matches the decision beats picking the most powerful tool every time.
Watch for Hidden Assumptions
Every calculator embeds assumptions about returns, inflation, longevity, and spending growth. Some display them openly — FIRECalc and NewRettlement-class tools let you change every one. Others bury them, and a confident-looking result built on a 7% real return can be worse than no result at all. Before trusting any output, find the assumptions page; if you can’t find it, treat the answer as rough.
Free Tools vs. Books vs. Paid Software
Free web tools are best for recurring check-ins because they’re fast. Books win on education — you’ll make better decisions because you understand the tradeoffs. Paid software wins on granularity once taxes and withdrawal sequencing enter the picture. Many readers will reasonably use one of each: a book to learn, a free tool to track, and premium software in the final five years before retirement.
Frequently Asked Questions
Are free retirement calculators accurate enough to trust?
Free calculators are only as accurate as the assumptions you feed them and they choose internally. Tools like Vanguard’s and Fidelity’s use sound Monte Carlo mathematics, so the engine isn’t the weak point — the inputs are. Most people misjudge their retirement spending, forget healthcare costs, or ignore taxes on withdrawals. A free tool with honest inputs beats a paid tool with guessed inputs. The danger is false precision: a 92% success probability displayed to one decimal place feels scientific even when the underlying spending estimate was made in thirty seconds. Use free calculators for direction, then validate with a second method before making an irreversible decision like retiring.
What’s the 4% rule, and should a calculator use it?
The 4% rule says you can withdraw 4% of your portfolio in year one, adjust for inflation annually, and have a high probability of your money lasting 30 years, based on historical U.S. market data. It’s a useful starting benchmark, but it’s a rule of thumb from one country’s past performance, and today’s lower bond yields and longer retirements strain it. Calculators that rely solely on the 4% rule — some books and quick web tools do — give you a number without testing whether your specific withdrawal rate would have survived bad market sequences. Tools like FIRECalc or any Monte Carlo calculator let you test withdrawal rates directly rather than accepting a fixed rule.
Should I use one calculator or several?
Several, used deliberately. Different calculators answer different questions: a savings-target tool tells you how much to accumulate, FIRECalc tells you whether your withdrawal rate survives bad decades, and a claiming-age tool settles Social Security timing. Running the same plan through a deterministic calculator and a Monte Carlo tool also exposes whether your result depends on an optimistic return assumption. The mistake to avoid is shopping for tools until one gives you the answer you want — that’s confirmation, not planning. Two or three tools with different methods, plus one educational resource like The Retirement Dilemma to interpret the outputs, is a solid stack.
When should I pay for retirement planning software?
Paid software earns its cost in roughly two situations: when taxes materially affect your plan, and when you’re within about ten years of retiring. Roth conversion ladders, capital gains harvesting, bracket management in low-income bridge years, and withdrawal sequencing across account types are decisions where free tools guess and paid tools compute. If your situation is a 401(k) plus Social Security and you’re twenty years out, free tools and a good book cover you. If you have a taxable brokerage, rental property, equity compensation, or a gap years before Medicare, NewRetirement-class software will pay for itself in better decisions.
How often should I recalculate my retirement plan?
Once a year is the right cadence for most people, ideally at the same time each year so comparisons are consistent. Recalculate sooner after any major life event — job change, inheritance, marriage, divorce, a big market move, or a change in your expected retirement age. Automatic tools like Empower or Fidelity’s planner update continuously, which is convenient but can encourage overreacting to short-term market swings; a scheduled annual review with a manual tool often produces better decisions than daily tracking. The point of recalculation isn’t the number itself — it’s noticing when your trajectory has drifted enough that your savings rate or planned retirement age should change.
Conclusion
If you take one approach from this comparison, make it matching the tool to the decision rather than hunting for a single all-purpose calculator.
Beginners and early-career savers should start with the Retirement Calculator book for a savings target, backed by Vanguard’s three-minute nest egg check. Pre-retirees within ten years of leaving work get the most from The Retirement Dilemma, whose fifteen calculators cover the decisions that actually determine whether a plan holds — supplemented by the Open Social Security calculator for claiming age. Detail-oriented planners and early retirees should invest in NewRetirement and stress-test with FIRECalc. Hands-off trackers with consolidated accounts will find Fidelity’s or Empower’s tools do the work quietly in the background. And anyone pricing guaranteed income should pull real annuity quotes before assuming what a pension or SPIA is worth. Whichever route you choose, run your plan through at least one tool whose assumptions you can see and change — that habit matters more than which calculator wins any slot on this list.