
Use this guide to choose financial planning books that match your current knowledge and money goals, then turn the useful ideas into manageable actions. It is for readers who are new to personal finance and want a starting point for budgeting, debt, saving, investing, or retirement planning without trying to learn everything at once. Plan for about 2-4 hours to compare books and begin reading, followed by several weeks to work through one book and apply its advice.

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included

Personal Finance For Dummies
- ✔ Format: Book
- ✔ Category: Personal finance
- ✔ Intended reader: General beginner audience
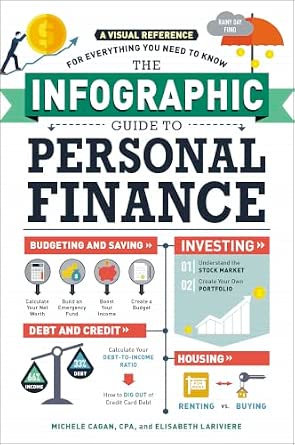
The Infographic Guide to Personal Finance: A Visual Reference for Everything You Need to Know
- ✔ Format: Visual reference guide
- ✔ Series: Infographic Guide series
- ✔ Subject: Personal finance

Financial Literacy for Young Adults Simplified
- ✔ Format: Book
- ✔ Intended reader: Young adults
- ✔ Topics: Money management, saving, and investing
Difficulty: Beginner | Time: 2-4 hours to select and start a book; several weeks to read and apply it
What You’ll Need
Tools & Materials:
- A notebook, notes app, or spreadsheet
- Access to a public library, bookstore, or bookseller with sample pages
- A calendar or task list for recording follow-up actions
Knowledge:
- No financial planning background is required
- A rough idea of your main money question or goal is helpful
Write down your country or region before choosing a book. Tax rules, retirement accounts, credit systems, and investment products differ by location, so advice tied to one country may not apply elsewhere. Books provide general education, not a personal financial, tax, or legal recommendation.
Personal Finance For Dummies
For a beginner who wants one approachable place to start, Personal Finance For Dummies takes our top spot. Its broad personal-finance positioning makes it the most natural general-purpose choice in this group: we can begin without needing to fit a particular age or learning style first. Compared with The Infographic Guide to Personal Finance, this pick is better suited to someone looking for a conventional guide rather than a visual reference. Compared with Financial Literacy for Young Adults Simplified, its apparent appeal is less tied to one life stage.The tradeoff is that the supplied product information does not specify its chapter list, planning tools, or particular topics. We should therefore choose it for its accessible, general beginner framing—not assume it provides a detailed plan for every financial decision. Readers who learn most quickly through graphics may prefer the Infographic Guide, while young adults wanting an explicitly age-focused perspective may find the third book more directly aligned. Still, as the broadest entry point implied by its title, it is the clearest choice for a first pass through personal finance.
Pros:
- Positioned as an approachable personal-finance guide for beginners
- Offers the broadest general-purpose fit in this three-book comparison
- Does not signal a narrow age-group focus in its title
- Works as a starting point for readers still deciding which money topics to explore
Cons:
- The available product details do not confirm its exact topic coverage or learning tools
- Less specifically differentiated than the visual guide or the young-adult-focused option
Best for: Beginners who want a general introduction to personal finance without choosing a book aimed at a specific age group or visual learning style.
Not ideal for: Readers who specifically want an infographic-led format, a young-adult-focused guide, or verified detail about particular chapters and planning tools before choosing.
Bottom line: We recommend Personal Finance For Dummies as the most flexible first pick for beginners who want a general personal-finance starting point.
“We recommend Personal Finance For Dummies as the most flexible first pick for beginners who want a general personal-finance starting point.”
The Infographic Guide to Personal Finance: A Visual Reference for Everything You Need to Know
The Infographic Guide to Personal Finance has the clearest format distinction in the lineup: it presents itself as a visual reference covering a broad range of personal-finance material. That makes it a useful alternative for readers who find a visual overview easier to scan than a conventional text-led guide. Where Personal Finance For Dummies is our more flexible general starting point, this book’s appeal is its stated visual approach. Its membership in the Infographic Guide series reinforces that identity.Visual organization can make a broad subject feel more approachable, especially when we want to revisit a topic rather than read straight through. But this format is not automatically best for every beginner. Readers who want extended explanations or a strongly age-specific discussion may be better served by one of the other options, and the available description does not confirm the precise topics or level of detail in individual sections. We rank it second because its learning-style advantage is clear, while its usefulness as a complete step-by-step introduction is harder to establish from the supplied information.
Pros:
- Explicitly designed as a visual reference
- Covers a broad personal-finance subject area according to its description
- Offers a different learning format from the other two picks
- Part of the Infographic Guide series
Cons:
- Visual summaries may not provide the depth some beginners want
- The supplied details do not identify specific chapters or planning exercises
- Less tailored to a particular life stage than the young-adult guide
Best for: Beginners who prefer visual explanations and want a broad personal-finance reference they can scan or revisit.
Not ideal for: Readers who want a confirmed step-by-step planning program, extended text explanations, or guidance tailored to young-adult life stages.
Bottom line: We would choose this book over the general guide when visual scanning is a meaningful learning advantage, while treating it as a reference rather than a confirmed full planning program.
“We would choose this book over the general guide when visual scanning is a meaningful learning advantage, while treating it as a reference rather than a confirmed full planning program.”
Financial Literacy for Young Adults Simplified
Financial Literacy for Young Adults Simplified is the most focused recommendation here. Its description specifically names money management, saving, and investing, and frames those subjects around building a secure and financially independent future. That audience focus is its main advantage: young adults who want financial basics connected to independence may find it more immediately relevant than either the general-purpose Personal Finance For Dummies or the visual reference.That same focus limits its reach. Beginners outside the young-adult audience may prefer the more broadly positioned first pick, and readers who want a visual format should look to the Infographic Guide instead. The available description also does not say how deeply the book treats each subject, whether it includes exercises, or how it handles different financial circumstances. We place it third overall not because its focus is a weakness for its intended readers, but because it is less universally applicable across the full beginner audience. For a young adult choosing a first money book, however, that specificity can be exactly the point.
Pros:
- Explicitly aimed at young adults
- Covers money management, saving, and investing according to the description
- Connects financial learning with security and independence
- Offers a more audience-specific perspective than the other two books
Cons:
- Its young-adult focus may not suit every beginner
- The supplied details do not establish the depth of coverage for each subject
- Format, exercises, and specific planning methods are not stated
Best for: Young adults who want an introductory guide connecting money management, saving, and investing with financial independence.
Not ideal for: Older beginners seeking a broadly age-neutral introduction, or readers who prioritize a visual reference format.
Bottom line: For young adults seeking money guidance framed around independence, this is the most directly targeted option, though it is less universal than our top-ranked pick.
“For young adults seeking money guidance framed around independence, this is the most directly targeted option, though it is less universal than our top-ranked pick.”
As an Amazon Associate we earn from qualifying purchases.
Before You Start
Gather only the information needed to identify your learning goal. You do not need to share account numbers, passwords, or other sensitive details with a bookseller, online quiz, or note-taking tool. If you are facing urgent debt collection, possible bankruptcy, tax deadlines, or a major investment decision, use a qualified local professional or nonprofit service alongside general reading.
Decide how much time you can read each week. A short, focused reading routine is more useful than buying several books and leaving them unopened.
Step-by-Step Instructions
Step 1: Name the money question you want to answer
Write one sentence describing the most useful result you want from your first book. Make it specific, such as “I want to make a monthly budget that includes irregular bills,” “I need a plan to pay down credit-card debt,” or “I want to understand basic, long-term investing.” If you have several goals, put them in order and start with the one that affects your next decision.
Separate a practical problem from a broad interest. “Learn about money” is difficult to act on; “understand how to build an emergency fund while paying debt” gives you a clear way to judge whether a book fits.
Tip: If bills or high-interest debt are causing immediate strain, prioritize cash flow and debt basics before reading about advanced investing strategies.
Check: You have one main learning goal and, if needed, a short ranked list of later topics.
Step 2: Choose the right kind of book for that goal
Match your goal to a book’s main subject. For everyday money management, look for budgeting, cash flow, saving, and debt. For investing, choose an introductory book that explains risk, diversification, fees, and long-term behavior. For retirement, look for a beginner guide that covers saving habits and the relevant account types in your country.
Read the description, contents page, and introduction when available. Check that the book teaches the subject you need rather than merely mentioning it. A broad personal finance guide can help you orient yourself, while a focused book may work better when you already have a specific question.
Tip: A book can cover useful general habits while still being a poor source for local tax or retirement-account rules. Check the geographic scope before relying on those details.
Check: The book’s stated audience and chapter headings clearly match your main goal.
Look up the author’s background and identify what kind of expertise supports the book: relevant professional work, research, teaching, or clearly described personal experience. Check the publication date, especially for books discussing tax law, account rules, interest rates, or current financial products.
Scan sample pages for explanations that distinguish general principles from personal opinion. Prefer authors who describe trade-offs, acknowledge uncertainty, and explain risks. Treat claims of guaranteed returns, effortless wealth, secret systems, or pressure to buy an author’s product as reasons to pause and verify the material elsewhere.
Tip: An older book may still explain durable habits well, but verify current rules with an official government source or qualified local professional.
Check: You can explain why the author is a suitable guide and which parts of the advice may need current local verification.
Step 4: Compare a small shortlist before choosing
Select two or three candidate books, then compare them on subject fit, reading level, location, publication date, and practical usefulness. Read a sample chapter from each if possible. Notice whether the author defines unfamiliar terms, gives examples, and explains what a beginner can do next.
Use library previews or sample pages before paying. A book with an approachable title may still assume knowledge you do not have, while a more modestly titled guide may explain the basics more clearly. Choose one primary book rather than buying a stack at once; you can add a second source after you know what remains unclear.
Tip: Reviews can reveal whether a book is readable, but reader reviews are not proof that its financial claims are accurate.
Check: You have chosen one book for a clear reason and know how to access it.
Step 5: Set a reading routine and capture useful ideas
Choose a realistic reading schedule, such as 20 minutes three times a week, and add it to your calendar. At the start of each session, keep your original goal visible. As you read, record only three kinds of notes: an idea you understand, a question to verify, and an action you might take.
Write unfamiliar terms in plain language rather than copying long passages. Mark any advice that depends on your income, debt, location, or risk tolerance. Do not treat an example household’s numbers as a recommendation for your own finances.
Tip: If the book feels too dense, read a short section at a time and define terms as they appear. You do not need to understand every technical detail before making progress on a basic goal.
Check: Your calendar contains reading sessions, and your notes separate understood ideas from open questions and possible actions.
Step 6: Verify advice that depends on your circumstances
Before acting on guidance about taxes, debt settlement, insurance, investing, or retirement accounts, check whether it applies where you live and to your situation. Use official government, regulator, or nonprofit sources for current rules. For personal advice involving significant sums or legal obligations, speak with a qualified professional whose credentials and fees you can verify.
Pay particular attention to recommendations involving a specific product, lender, broker, or service. Find out whether the author or adviser has a financial interest in it, and compare costs, risks, and alternatives before committing.
Tip: General books are useful for learning questions to ask; they do not replace a review of your personal circumstances.
Check: You have identified which advice is general, which details need a current local source, and which decisions call for personal advice.
Step 7: Turn one lesson into a small, measurable action
Choose one low-risk action that directly supports your goal. Examples include listing monthly bills, tracking spending for two weeks, setting a savings target, or comparing the fees on accounts you already use. Write down what you will do, when you will do it, and how you will tell whether it helped.
For decisions with lasting or substantial effects, such as changing investments, taking a loan, or altering insurance, do not act solely because one book recommends it. Gather current information and seek qualified guidance when appropriate. Review your action after a set period and decide whether to continue, revise, or ask a more specific question.
Tip: Keep the first action small enough to complete in a week. A completed step gives you clearer questions for your next reading session.
Check: You have one written action with a deadline and a simple way to review its result.
Common Mistakes to Avoid
- Buying several books before deciding what you need to learn. — Choose one main goal, compare a short list, and borrow or preview the leading option before buying.
- Following advice about accounts, taxes, or investments without checking its location and date. — Confirm the book’s geographic scope and publication date, then verify changing rules through official local sources.
- Trying to adopt every suggestion at once. — Select one practical, low-risk action and review how it works before adding another.
- Treating a personal story or promised return as proof that a strategy will work for everyone. — Look for discussion of risk, costs, trade-offs, and evidence; be wary of guarantees and sales pressure.
Troubleshooting
Problem: The book is full of terms you do not understand.
Solution: Pause at each unfamiliar term, write down the plain-language question it raises, and consult a beginner glossary or reputable educational source. If most chapters remain inaccessible, switch to a more introductory book rather than forcing your way through it.
Problem: The advice appears outdated or refers to accounts you cannot use.
Solution: Check the book’s location and publication date. Keep any durable general lessons, but confirm current eligibility, tax treatment, fees, and rules with official sources in your area before taking action.
Problem: The book promotes a product, course, or service alongside its advice.
Solution: Pause before paying or sharing personal information. Check the author’s financial relationship, compare independent sources, review fees and cancellation terms, and avoid pressure-based decisions.
Problem: You finish a chapter but still do not know what to do next.
Solution: Restate your goal, identify the chapter’s most relevant idea, and turn it into a question or a small action. If the book does not provide clear examples or steps for your goal, choose a more practical source.
What Success Looks Like
You have selected a book that matches a specific beginner-level goal, checked that its audience and location fit your needs, and identified claims that require current verification. You have a realistic reading schedule, notes that separate facts from questions, and at least one small action with a deadline. You can explain what to verify before making a consequential financial decision.
Next Steps
Complete your first action and review the result on the date you chose. Add unresolved questions to a short list, then use a reliable local source or a second focused book to answer them. Keep the book’s notes with your budget or planning records, and revisit them when your income, debt, goals, or local rules change. If you need advice tailored to your circumstances, check a professional’s qualifications, services, and fee structure before hiring them.
Frequently Asked Questions
Should I start with a general personal finance book or a book about one topic?
Start with a focused book if you have a specific pressing goal, such as budgeting or paying off debt. Choose a general beginner guide if you need an overview and do not yet know which area to tackle. Either way, check the contents page to confirm it covers the skills you need.
How can I tell whether a financial planning book is beginner-friendly?
Read a sample section. A beginner-friendly book defines terms, explains steps in order, uses realistic examples, and does not assume that you already know investment or tax jargon. If the sample leaves key ideas unexplained, look for a more introductory title.
Are older financial books still useful?
They can be useful for durable topics such as spending habits, goal setting, and the effect of costs over time. Verify dated details about tax rules, financial products, account eligibility, and regulations through current official sources before relying on them.
Can a book replace a financial adviser?
A book can teach general concepts and help you prepare questions, but it cannot review your full circumstances or provide personalized recommendations. For complex tax, legal, debt, insurance, or investment decisions, consider a qualified professional who serves your location and clearly discloses fees and conflicts of interest.
What should I do if a book recommends a strategy that feels too risky?
Do not act until you understand the possible losses, costs, time commitment, and alternatives. Verify the recommendation with an independent, reputable source, and seek qualified personal advice if the decision could have a major effect on your finances.
Halloween Picks
halloween
As an affiliate, we earn on qualifying purchases.